North America Confectionery Market Research Report – Segmentation by Product Type (Chocolate Confectionery, Sugar Confectionery, Gum Products, and Others); By Distribution Channel (Supermarkets/Hypermarkets, Convenience Stores, Online Retail, and Specialty Stores); and Region - Size, Share, Growth Analysis | Forecast (2025– 2030)
North America Confectionery Market Size (2025-2030)
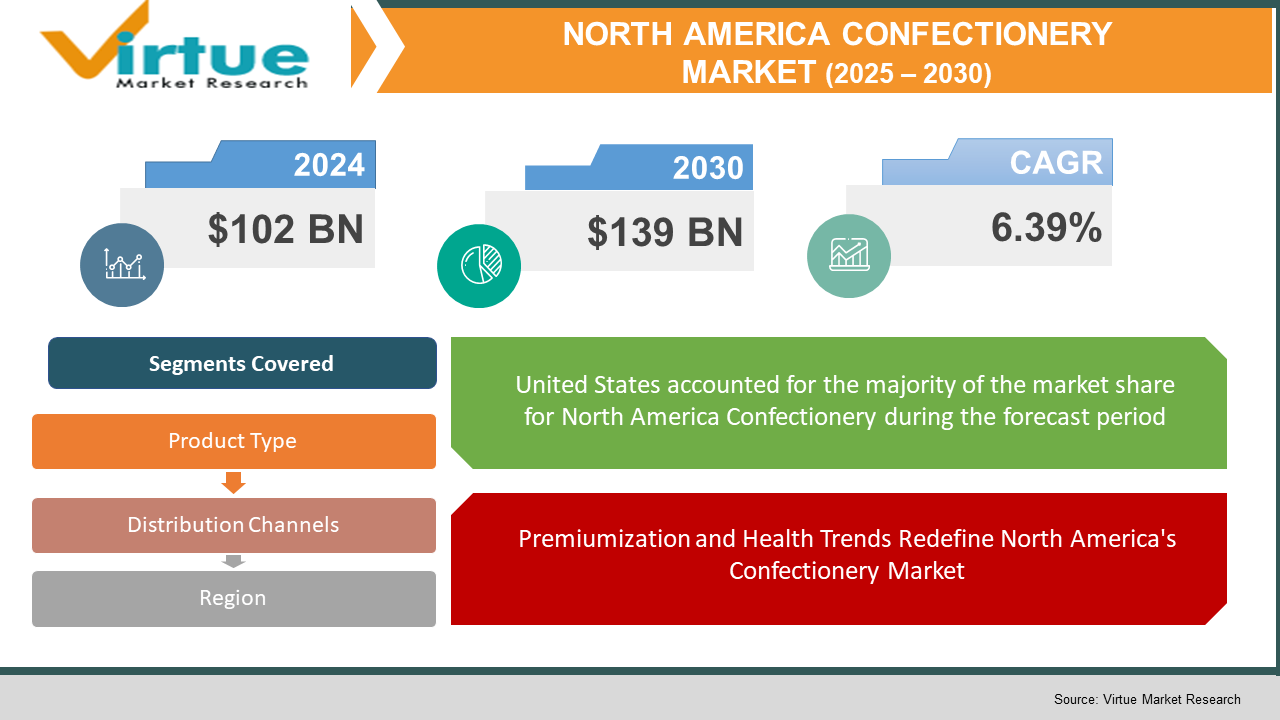
The North America Confectionery Market was valued at USD 102 billion and is projected to reach a market size of USD 139 billion by the end of 2030. Over the forecast period of 2023-2030, the market is projected to grow at a CAGR of 6.39%.
The confectionery industry in North America represents a mature yet continuously evolving market characterized by innovation in Flavors, ingredients, and production technologies. Consumer preferences are shifting toward premium, artisanal, and healthier confectionery options while maintaining indulgence as a core attribute. The market encompasses a wide range of products including chocolates, candies, gums, and pastries, with major players constantly adapting their product portfolios to meet changing consumer demands for natural ingredients, functional benefits, and sustainable packaging solutions.
Key Market Insights:
According to the National Confectioners Association survey, approximately 81% of American adults purchase confectionery products, with the average consumer spending $104.92 annually on chocolate products and $38.75 on non-chocolate confections, demonstrating the category's strong market penetration.
Premium chocolate sales have increased by 23% over the past three years, outpacing standard chocolate products which grew at only 4.6%, indicating a significant consumer shift toward higher-quality indulgence experiences despite higher price points in the $8-15 range for specialty chocolate bars.
Functional confectionery products containing added vitamins, protein, or adaptogens captured 14.3% market share in 2022, growing at 17.8% annually since 2020, with 62% of millennial consumers reporting willingness to pay a premium of up to 30% for confections offering health benefits beyond simple indulgence.
Seasonal confectionery sales account for 44% of annual category revenue in North America, with Halloween generating $4.9 billion, Christmas $4.4 billion, Easter $3.7 billion, and Valentine's Day $2.4 billion in confectionery sales, making seasonal product innovations critical drivers for manufacturer growth strategies.
North America Confectionery Market Drivers:
Premiumization and Health Trends Redefine North America's Confectionery Market.
North American consumers are increasingly seeking premium confectionery experiences, with 67% of surveyed consumers expressing willingness to pay more for products with high-quality ingredients and distinctive flavor profiles. This premiumization trend has led to a 15.2% annual growth in artisanal chocolate sales since 2020, compared to just 2.8% growth in mass-market chocolate products. Confectionery manufacturers have responded by introducing limited-edition collections, single-origin chocolate products, and hand-crafted confections that command 40-60% higher retail prices than standard offerings. The health-conscious consumer segment has simultaneously expanded, with 72% of millennials and Gen Z consumers actively seeking confectionery products with natural ingredients, reduced sugar content, and functional benefits. Products labelled "better-for-you" have seen remarkable 22.4% sales growth annually, with sugar-free confections expanding market share from 6.1% to 11.3% over the past three years. Manufacturers have invested heavily in R&D, with the top five confectionery companies collectively allocating $1.8 billion in 2024 toward alternative sweetener research and functional ingredient integration. Dark chocolate with high cocoa content (70%+) has experienced a 31% sales increase since 2020, driven by consumer awareness of its antioxidant properties and lower sugar content.
The strategic expansion of digital retail channels and innovative in-store merchandising approaches are revolutionizing confectionery distribution and consumer engagement.
E-commerce sales of confectionery products have grown exponentially in North America, with online channel revenue increasing by 86% between 2020 and 2022, reaching $7.1 billion annually. Direct-to-consumer subscription models for premium chocolate and specialty confections have attracted 4.2 million subscribers across major platforms, generating predictable revenue streams and valuable consumer data for manufacturers. Approximately 58% of confectionery consumers now research products online before purchase, while 36% regularly buy confectionery through digital channels, primarily seeking unique products unavailable in local retail environments. In physical retail locations, confectionery companies have invested in innovative merchandising technology, including digital shelf displays that have demonstrated a 17% sales lift in pilot programs and interactive sampling stations that boost conversion rates by 23% compared to traditional displays. Cross-merchandising strategies linking confectionery with complementary categories like coffee, wine, or entertainment products have shown average basket value increases of $12.40 per transaction.
North America Confectionery Market Restraints and Challenges:
The major challenge to the industry is that of health concerns regarding sugar consumption and government regulations.
Health concerns represent significant market headwinds, with 64% of consumers actively attempting to reduce sugar consumption according to recent survey data. Government regulations targeting sugar content and marketing restrictions, particularly those aimed at products advertised to children, have forced manufacturers to reformulate approximately 31% of their product portfolios at considerable expense. The industry faces substantial raw material challenges, with cocoa prices increasing 28% since 2020 due to climate change impacts in growing regions, while vanilla prices have fluctuated up to 500% in five-year cycles. Labor shortages throughout the supply chain have increased production costs by 12.3% since 2019, with specialized confectionery manufacturing positions remaining unfilled for average periods of 3.2 months. Meanwhile, the market faces fierce competition from alternative snacking categories, with protein bars, fruit snacks, and savory options capturing 14% of traditional confectionery occasions according to consumer substitution studies
North America Confectionery Market Opportunities:
The integration of sustainability practices presents substantial growth opportunities, with 73% of consumers expressing willingness to pay premiums of 10-15% for environmentally responsible confectionery products. Manufacturers implementing traceable cocoa sourcing have reported sales increases averaging 18% compared to conventional alternatives. The functional confectionery segment is projected to reach $9.7 billion by 2028, with products incorporating adaptogens, probiotics, and nootropic ingredients showing particular promise among wellness-oriented consumers. International flavor innovations present significant growth vectors, with globally-inspired confections experiencing 24% annual growth as North American consumers seek authentic experiences from regions like Japan, India, and the Middle East.
NORTH AMERICA CONFECTIONERY MARKET REPORT COVERAGE:
REPORT METRIC
DETAILS
Market Size Available
2024 - 2030
Base Year
2024
Forecast Period
2025 - 2030
CAGR
6.39%
Segments Covered
By Product Type, Distribution Channel and Region
Various Analyses Covered
Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities
Regional Scope
North America, USA, MEXICO, CANADA
Key Companies Profiled
Mars Inc., Hershey, Mondelez International, Nestlé, and Ferrero
North America Confectionery Market Segmentation:
North America Confectionery Market Segmentation: By Product Type:
Chocolate Confectionery
Sugar Confectionery
Gum Products
Others
The chocolate confectionery segment dominated the North American market with approximately 58.7% revenue share, valued at $30.9 billion. Premium chocolate products grew at 9.2% annually, significantly outpacing the 2.1% growth of standard chocolate offerings. Dark chocolate specifically experienced 11.4% growth, driven by health-conscious consumers seeking higher cocoa content and antioxidant properties. Manufacturers have responded with single-origin products, bean-to-bar offerings, and innovative flavor combinations incorporating spices, herbs, and functional ingredients that command 40-60% higher retail prices than conventional chocolates.
The sugar confectionery segment held 27.3% market share in 2022, with hard candies, gummies, and pastilles collectively representing $14.4 billion in retail sales. This segment has undergone significant transformation with 68% of new product launches featuring natural colors and flavors, compared to just 31% in 2018. Functional gummies containing vitamins, minerals, and adaptogens have emerged as the fastest-growing sub-segment, expanding at 21.7% annually as consumers seek treat options with perceived health benefits. Major manufacturers have responded by acquiring specialized wellness confectionery brands, with acquisition premiums averaging 3.7x annual revenue for companies with established functional candy portfolios.
North America Confectionery Market Segmentation: By Distribution Channel
Supermarkets/Hypermarkets
Convenience Stores
Online Retail
Specialty Stores
Supermarkets and hypermarkets remained the dominant distribution channel for confectionery in North America, accounting for 42.6% of total sales in 2024. These retailers leverage extensive shelf space, strategic merchandising locations (including checkout areas that generate 28% of impulse confectionery purchases), and cross-promotional opportunities to drive category sales. Data analytics implementation in this channel has improved inventory management and promotional effectiveness, with targeted confectionery promotions delivering 15-22% higher returns on investment when aligned with complementary product categories and seasonal events.
Online retail represents the fastest-growing distribution channel, expanding at 23.4% annually and reaching 16.8% market share in 2022. This channel's growth is driven by subscription services, which retain 68% of customers beyond six months, and direct-to-consumer platforms offering exclusive products unavailable in traditional retail environments. Digital retail enables efficient targeting of niche consumer segments, with 41% of online confectionery shoppers purchasing specialty products like international sweets, craft chocolates, and nostalgic candies that have limited brick-and-mortar distribution. Manufacturers investing in optimized e-commerce packaging and temperature-controlled shipping solutions have reduced damage rates from 11.2% to 2.7%, significantly improving customer satisfaction and repeat purchase rates in this rapidly expanding channel.
North America Confectionery Market Segmentation: Regional Analysis:
United States
Canada
Mexico
The United States dominated the North American confectionery market, accounting for 78.3% of regional sales at $41.2 billion. American consumers demonstrate the highest per capita confectionery consumption in the region at 19.6 pounds annually, with particularly strong seasonal purchasing patterns that generate 46% of annual sales during key holidays. The premium segment has shown remarkable growth in urban markets, with specialty chocolate shops experiencing 12.3% annual revenue increases in metropolitan areas with populations over 1 million. Regional preferences are pronounced across the country, with the Northeast showing 27% higher consumption of dark chocolate products, while the South demonstrates 18% stronger performance in gummy and chewy candy categories.
Canada represented 13.5% of the North American confectionery market in 2022, with distinctive consumption patterns including 24% higher dark chocolate preference and 17% lower gum product purchases compared to U.S. consumers. The Canadian market has embraced sustainability initiatives more rapidly, with eco-friendly packaged products gaining 31% market share compared to 19% in the United States. Provincial regulations affecting sugar content labeling have accelerated reformulation efforts, with 38% of confectionery products in Canada featuring reduced sugar formulations compared to 24% in the broader North American market. The country's cultural diversity has supported strong performance of internationally inspired confections, which represent 14.7% of category sales compared to 9.3% in the United States.
COVID-19 Impact Analysis on the North America Confectionery Market:
The COVID-19 pandemic fundamentally altered North American confectionery consumption patterns, with at-home indulgence occasions increasing 37% during peak lockdown periods as consumers sought comfort foods amid uncertainty. Premium chocolate sales surged 19.2% in 2020-2021 despite economic pressures, reflecting consumers' willingness to spend on affordable luxuries when other experiential categories were unavailable. Distribution channels underwent rapid transformation, with e-commerce penetration in the confectionery category accelerating by approximately five years against pre-pandemic projections, reaching 14.3% of sales by 2021 compared to just 5.7% in 2019.
Latest Trends/ Developments:
The adoption of upcycled ingredients in confectionery products has gained significant traction, with 27 major manufacturers introducing products utilizing cocoa fruit pulp, imperfect nuts, and other previously discarded food components, achieving waste reduction of 14-22% while appealing to environmentally conscious consumers who demonstrate 28% higher brand loyalty to companies with transparent sustainability practices.
Hershey's acquisition of Lily's Sweets for $425 million represents the accelerating consolidation of mainstream manufacturers and better-for-you confectionery brands, providing established companies immediate access to growing market segments while allowing innovative brands to leverage large-scale distribution networks and marketing resources that drove 37% sales growth for acquired brands within their first year under corporate portfolios.
Key Players:
The Hershey Company
Mondelēz International
Mars, Incorporated
Ferrero Group
Nestlé S.A.
General Mills, Inc.
Lindt & Sprüngli AG
Perfetti Van Melle
Tootsie Roll Industries
Ghirardelli Chocolate Company
To Learn more about this report,
Global automotive lighting refers to all vehicle lighting systems, from headlamps that illuminate the road to taillights that communicate movements. They guarantee motorists and other road users alike safety, visibility, and style. While taillights frequently use LEDs for improved visibility, headlights are available in a variety of technologies, including LED and laser. Interior illumination, DRLs, and signal lights all have a role to play. This market, which was estimated to be worth $33.64 billion in 2022, is anticipated to rise to $67.39 billion by 2030 because of laws, luxury tastes, safety concerns, and technological developments like OLED taillights and adaptive headlights. Anticipate a future dominated by intelligent, connected, personalized, and sustainable lighting systems that enhance the safety, efficiency, and aesthetic appeal of automobiles.
Key Market Insights:
Car lighting works its magic to provide safety, visibility, and style. Headlights cut through the night, taillights express intent, and interiors shine with comfort. The billion-dollar global business is expected to rise due to consumer demand for high-end experiences, safer roads, and cutting-edge technology. Imagine dynamic messages being painted by taillights, headlights that adjust to the road, and interiors that customize their atmosphere. Driven by technological advancements like linked systems and laser beams, this future is calling. Anticipate even more visually attractive, environmentally friendly, and intelligent lighting to illuminate the way ahead, making cars safer, more efficient, and unquestionably cooler.
Global Automotive Lighting Market Drivers:
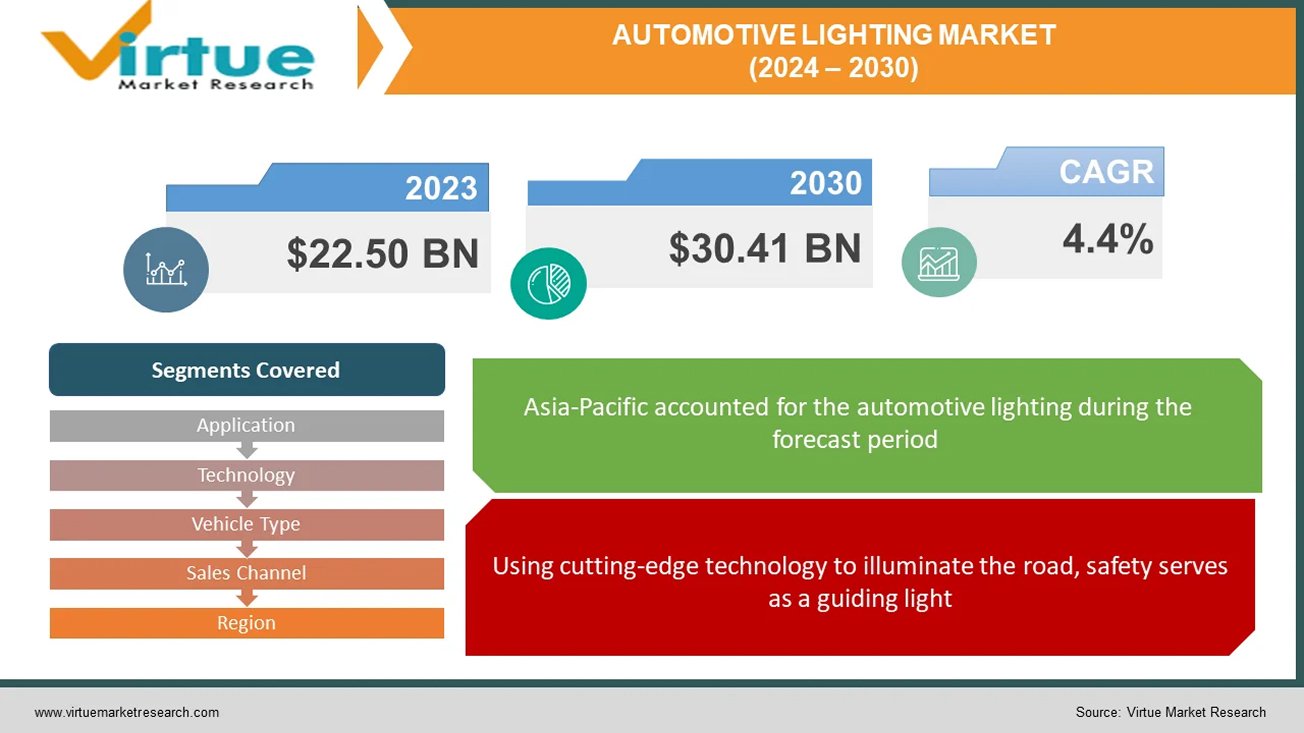
Using cutting-edge technology to illuminate the road, safety serves as a guiding light.
In the market for automobile lighting, safety is the driving force behind demand from the public and laws. While automated high beams smoothly react to traffic, adaptive headlights modify their beams so as not to blind other people. With visually striking displays, dynamic taillights convey intentions for braking and turning. Beyond these developments, integrated pedestrian identification and lane departure alerts will soon make roads safer and brighter for everyone.
Beyond Performance-Based Luxuries Redefined by Light.
Luxurious automobile lighting creates a distinct visual identity that goes beyond simple illumination. Personalized interior lighting customizes the driving experience by setting the mood with a range of colours and intensities, while intricate designs and distinctive DRLs modify exteriors. As you approach your automobile at night, welcoming lights lead the way, resulting in an interior that is perfectly lit. Not only is this symphony of light aesthetically pleasing, but it also stands as a tribute to luxury. Upcoming developments like gesture-controlled lighting and holographic displays promise to further enhance the experience.
Fuel Efficiency Takes the Lead: Illuminating Sustainability
The worldwide automotive lighting market is undergoing a significant transition towards energy-efficient solutions, as environmental concerns gain prominence. LED technology is leading the way, providing a ray of hope for the environment and drivers alike. LED lights beam brighter and use a lot less energy than conventional halogen lamps. There are some tangible advantages to this. For drivers, this translates to increased fuel economy, which lowers petrol prices and lessens reliance on fossil fuels. Greater air quality and a reduction in the transport sector's contribution to climate change are the results of reduced overall emissions.
To Learn more about this report,
Global Automotive Lighting Market Restraints and Challenges:
Although the global automotive lighting business is booming, there are still unknowns. Difficulties impede growth even as innovation propels it with eye catching features like laser beams and adaptable headlights. These technologies are luxury items due to their high cost and difficult integration, which puts producers' abilities to the test. The worldwide patchwork created by unclear legislation limits the potential of innovation. Durability issues persist, particularly when complex systems are subjected to challenging conditions. Ultimately, a lot of drivers still don't fully understand how these improvements can help them. Together, we can overcome these obstacles. The keys to reducing costs are improved production, more seamless integration, and unified regulations. Their full potential can be realized by educating customers about the safety, efficiency, and aesthetic value of these lighting wonders. By working together, we can pave the way for an even brighter and safer future for vehicle lighting.
Global Automotive Lighting Market Opportunities:
It is made possible by advanced LED technology, which gives drivers the ability to customize their illumination for the highest level of comfort and flair. Consumers that care about the environment want greener products, and vehicle lighting complies. While solar- and self-powered lighting technologies offer a future powered by clean energy, energy-efficient LEDs lower pollution. The advent of connected lighting systems heralds a new age. Envision automobiles interacting with infrastructure and one another to minimize accidents and enhance traffic efficiency. Integrated headlights with pedestrian recognition provide unmatched safety, while dramatic taillights with eye-catching displays alert onlookers to your intentions. The possibilities are endless in the future. Gesture-controlled interior illumination, holographic displays projected onto the road, and even light fixtures with self-healing capabilities.
AUTOMOTIVE LIGHTING MARKET REPORT COVERAGE:
To Learn more about this report,
Global Automotive Lighting Market Segmentation: By Application
Exterior Lighting
Interior Lighting
Due to laws requiring safety features like headlights, taillights, and brake lights, exterior lighting presently holds the most market share in the vehicle lighting industry. The dominance of this market is partly attributed to advancements in safety-focused technologies such as adaptive headlights and daytime running lights. The market value of external lighting is increased by the quick adoption of technology like LED bulbs and laser lights, which improve performance and aesthetics. Conversely, the interior lighting market is expected to increase at the fastest rate in the upcoming years. Innovations like ambient lighting and technology breakthroughs like LED and OLED displays, driven by consumer demand for comfort and personalisation, open new possibilities. The spread of sophisticated interior lighting systems is further driven by the growing emphasis on safety and the expansion of the luxury car market.
Global Automotive Lighting Market Segmentation: By Technology
Halogen
LED (Light-Emitting Diode)
Xenon
Emerging Technologies
The worldwide vehicle lighting market is currently dominated by halogen because of its more affordable price, advanced technology, and useful illumination. With its dependable supply chain and affordable option for manufacturers and cost-conscious customers, halogen holds the biggest market share. The fastest-growing market right now is LEDs, which are predicted to shortly overtake halogen. The rapid expansion of LEDs is driven by their higher efficiency, longer lifespan, flexibility in design, and technological breakthroughs including enhanced brightness. Because LEDs use less energy and produce fewer emissions and better fuel economy, they are becoming more and more popular in the changing automotive lighting market.
Global Automotive Lighting Market Segmentation: By Vehicle Type
Passenger Cars
Commercial Vehicles
Passenger automobiles rule the worldwide automotive lighting market. The sheer number of passenger cars produced which surpasses that of business vehicles and fuels the need for lighting systems is the primary cause of this popularity. The growing demand for personal automobiles in developing nations is a result of rising disposable income, which in turn drives the rise of the passenger car market. The importance that consumers place on safety and aesthetics elements helps to drive market expansion. But in the upcoming years, the market for electric and hybrid cars is expected to develop at the quickest rate. The exponential rise of the worldwide electric car market, which is still expanding and shows no signs of slowing down, is what is driving this surge. Specialised lighting solutions are required since electric and hybrid vehicles have different lighting requirements because of their specific functionality and design aesthetics.
Global Automotive Lighting Market Segmentation: By Sales Channel
OEM (Original Equipment Manufacturers)
Aftermarket
Most lighting systems sold nowadays are sold by OEMs (Original Equipment Manufacturers), primarily because manufacturers pre-install lighting systems in new cars. But in the next years, the aftermarket is expected to develop at the quickest rate. This spike in demand for replacement parts, especially lighting systems, can be linked to several variables, one of them being the average age of cars. The industry is expanding because of consumers' growing desire to personalise their cars with aftermarket lighting upgrades such LED upgrades and decorative lighting. The availability and affordability of technologies like adaptive headlights and laser lights in the aftermarket, together with other advancements in lighting technology, are driving demand even more. Moreover, the growing market for electric cars (EVs).
To Learn more about this report,
Global Automotive Lighting Market Segmentation: By Region
North America
Asia-Pacific
Europe
South America
Middle East and Africa
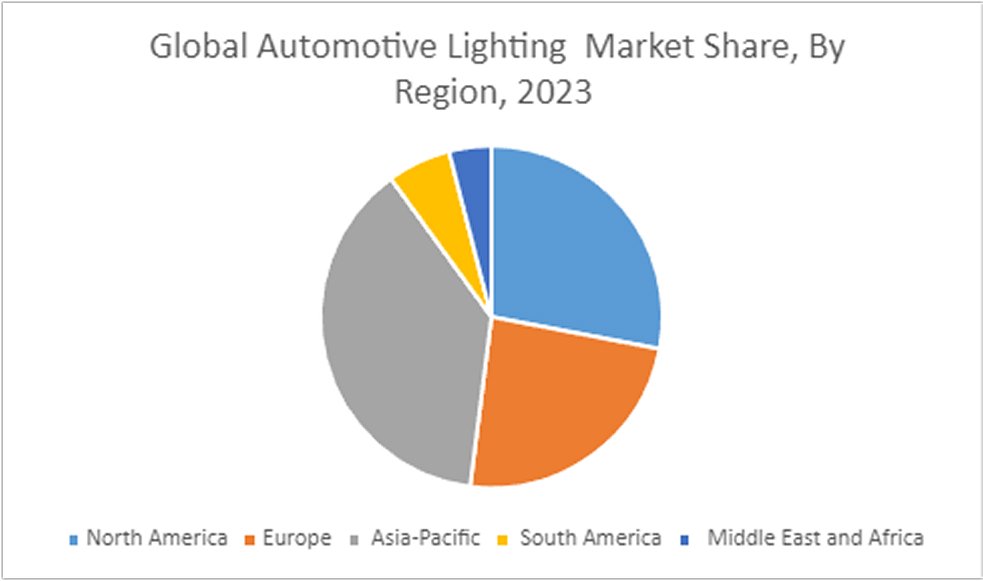
Throughout the forecast period, Asia Pacific is anticipated to be the automotive lighting market with the highest profitability. Over the past few years, Asia Pacific countries like China and India have seen notable increases in automotive manufacturing and sales, primarily in the medium-to premium luxury car segment. Asia Pacific is predicted to see an increase in the manufacturing of passenger cars, with India experiencing the strongest growth rate. Depending on the state of the national economy, the area offers a suitable selection of both high-end and cheap cars. For instance, there is a substantial demand for halogen, Xenon/HID, and LED since China and India produce more economy and mid-range automobiles. On the other hand, luxury car adoption rates are greater in South Korea and Japan, where LED lighting is the norm.
COVID-19 Impact Analysis on the Global Automotive Lighting Market:
A brief shadow was thrown by COVID-19 over the worldwide automotive lighting market. Production was stopped by lockdowns and supply chain disruptions, while luxury lighting upgrades were shelved by consumers on a tight budget. Resources became scarce, and R&D stagnated. Still, the market is recovering thanks to resurgent demand and rearranged priorities. While energy-efficient LEDs are being pushed towards adoption by sustainability, safety concerns are driving interest in features like pedestrian detection and adaptive headlights. The digital push of the epidemic creates opportunities for intelligent, networked lighting systems that may interact with infrastructure and other cars. Ultimately, the industry is positioned to shine brighter, focused on safety, sustainability, and a connected future, even though the pandemic dimmed its brilliance.
Recent Trends and Developments in the Global Automotive Lighting Market:
A development collaboration between OSRAM Continental and REHAU aims to incorporate lighting into external components, providing automobile manufacturers with innovative lighting options that improve functionality and design flexibility. For rear combination lamps, Hella unveiled a revolutionary lighting innovation called Hella FlatLight technology. A Memorandum of Understanding (MoU) was signed by Samvardhana Motherson Automotive Systems Group BV (SMRPBV), a division of Motherson Group, and Marelli Automotive Lighting to investigate a technology collaboration focused on intelligently lighted external body components. Valeo debuted their revolutionary 360° lighting system at the Shanghai Auto Show. This technology surrounds the car with a band of light, projecting instantaneous, clear signs that other drivers can see from a distance. Pedestrians, cyclists, and scooter riders are especially susceptible to these signals
Key Players:
AMS Osram
Cree
Hella
Hyundai Mobis
Koito
Luminus Devices
Magneti Marelli
Osram Licht AG
Stanley Electric
Valeo
Chapter 1. NORTH AMERICA CONFECTIONERY MARKET – SCOPE & METHODOLOGY
1.1. Market Segmentation
1.2. Scope, Assumptions & Limitations
1.3. Research Methodology
1.4. Primary Sources
1.5. Secondary Sources Chapter 2. NORTH AMERICA CONFECTIONERY MARKET – EXECUTIVE SUMMARY
2.1. Market Size & Forecast – (2025 – 2030) ($M/$Bn)
2.2. Key Trends & Insights
2.2.1. Demand Side
2.2.2. Supply Side
2.3. Attractive Investment Propositions
2.4. COVID-19 Impact Analysis Chapter 3. NORTH AMERICA CONFECTIONERY MARKET – COMPETITION SCENARIO
3.1. Market Share Analysis & Company Benchmarking
3.2. Competitive Strategy & Development Scenario
3.3. Competitive Pricing Analysis
3.4. Supplier-Distributor Analysis Chapter 4. NORTH AMERICA CONFECTIONERY MARKET - ENTRY SCENARIO
4.1. Regulatory Scenario
4.2. Case Studies – Key Start-ups
4.3. Customer Analysis
4.4. PESTLE Analysis
4.5. Porters Five Force Model
4.5.1. Bargaining Power of Suppliers
4.5.2. Bargaining Powers of Customers
4.5.3. Threat of New Entrants
4.5.4. Rivalry among Existing Players
4.5.5. Threat of Substitutes Players
4.5.6. Threat of Substitutes Chapter 5. NORTH AMERICA CONFECTIONERY MARKET - LANDSCAPE
5.1. Value Chain Analysis – Key Stakeholders Impact Analysis
5.2. Market Drivers
5.3. Market Restraints/Challenges
5.4. Market Opportunities Chapter 6. NORTH AMERICA CONFECTIONERY MARKET – By Product Type
6.1 Introduction/Key Findings
6.2 Chocolate Confectionery
6.3 Sugar Confectionery
6.4 Gum Products
6.5 Others
6.6 Y-O-Y Growth trend Analysis By Product Type
6.7 Absolute $ Opportunity Analysis By Product Type , 2025-2030
Chapter 7. NORTH AMERICA CONFECTIONERY MARKET – By Distribution Channel
7.1 Introduction/Key Findings
7.2 Supermarkets/Hypermarkets
7.3 Convenience Stores
7.4 Online Retail
7.5 Specialty Stores
7.6 Y-O-Y Growth trend Analysis By Distribution Channel
7.7 Absolute $ Opportunity Analysis By Distribution Channel , 2025-2030
Chapter 8. NORTH AMERICA CONFECTIONERY MARKET - By Geography – Market Size, Forecast, Trends & Insights
8.1. North America
8.1.1. By Country
8.1.1.1. U.S.A.
8.1.1.2. Canada
8.1.1.3. Mexico
8.1.2. By Distribution Channel
8.1.3. By Product Type
8.1.4. Countries & Segments - Market Attractiveness Analysis
Chapter 9. NORTH AMERICA CONFECTIONERY MARKET – Company Profiles – (Overview, Packaging Product, Portfolio, Financials, Strategies & Developments)
9.1 The Hershey Company
9.2 Mondelēz International
9.3 Mars, Incorporated
9.4 Ferrero Group
9.5 Nestlé S.A.
9.6 General Mills, Inc.
9.7 Lindt & Sprüngli AG
9.8 Perfetti Van Melle
9.9 Tootsie Roll Industries
9.10 Ghirardelli Chocolate Company
Fill out the form below and our team will get back to you shortly
FAQ's
The market includes chocolate, sugar confectionery (candies, gummies, mints), and gum products sold across retail, convenience stores, and online platforms.
Growth is driven by premiumization, innovation in Flavors, healthier variants, seasonal demand, and strong branding by major players
Major players include Mars Inc., Hershey, Mondelez International, Nestlé, and Ferrero
Yes, there is increasing demand for low-sugar, organic, vegan, and functional confectionery that fits wellness trends
Trending products include plant-based chocolates, artisanal candies, sugar-free alternatives, and personalized confectionery experiences
More related reports
Get expert-driven market research reports from a leading research partner to help you navigate the future of the global industry.
Report Code: VMR-18738 | Published Date: October 2025 | Format: Excel and PDF
The Middle East and Africa Cold Cuts Market was valued at USD 35.93 billion in 2024 and is projected to reach a market size of USD 110.55 billion by the end of 2030. Over the forecast period of 2025-2030, the market is p...
Report Code: VMR-18663 | Published Date: October 2024 | Format: Excel and PDF
The Arabica Sourced Bioactive Compounds in Coffee Market was valued at USD 340 Million in 2024 and is projected to reach a market size of USD 513 Million by the end of 2030.
Report Code: VMR-15690 | Published Date: August 2023 | Format: Excel and PDF
The Global Online Ready-to-Drink Cocktails Market was valued at USD 8.2 billion in 2024 and will grow at a CAGR of 12% from 2025 to 2030. The market is expected to reach USD 16.2 billion by 2030.
Report Code: VMR-2118 | Published Date: July 2024 | Format: Excel and PDF
The Global Beauty Drinks Market was valued at USD 2.2 billion in 2024 and will grow at a CAGR of 14% from 2025 to 2030. The market is expected to reach USD 4.8 billion by 2030.
Report Code: VMR-1283 | Published Date: March 2024 | Format: Excel and PDF
The global chocolate powdered drinks market was valued at USD 2.92 billion and is projected to reach a market size of USD 5.28 billion by the end of 2030. Over the forecast period of 2024–2030, the market is projected to...
“We received a complex piece of work for our niche market from Virtue Market research in short period of time. I appreciate the quality and content of the final files we received. Thanks for the support”
Medical Devices Company based in Europe
“We received a complex piece of work for our niche market from Virtue Market research in short period of time. I appreciate the quality and content of the final files we received. Thanks for the support”
Medical Devices Company based in Europe
“We received a complex piece of work for our niche market from Virtue Market research in short period of time. I appreciate the quality and content of the final files we received. Thanks for the support”
Medical Devices Company based in Europe
“We received a complex piece of work for our niche market from Virtue Market research in short period of time. I appreciate the quality and content of the final files we received. Thanks for the support”
Medical Devices Company based in Europe
“We received a complex piece of work for our niche market from Virtue Market research in short period of time. I appreciate the quality and content of the final files we received. Thanks for the support”
Medical Devices Company based in Europe
“We received a complex piece of work for our niche market from Virtue Market research in short period of time. I appreciate the quality and content of the final files we received. Thanks for the support”