
Industrial Lubricants Market
The market size was estimated at USD 77 billion in 2025, and is projected to reach 88.83 billion in 2030, growing at a CAGR of 2.9% from 2026 to 2030.
Explore reportThe Global Water-Based Metal Packaging Coatings Market was valued at USD 25.7 billion and is projected to reach a market size of USD 32.05 billion by the end of 2030. Over the forecast period of 2023-2030, the market is projected to grow at a CAGR of 2.8%.
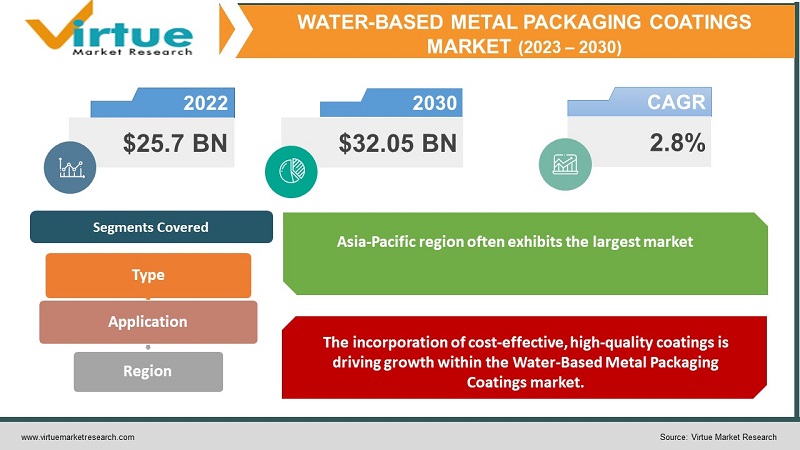
The Water-Based Metal Packaging Coatings market is experiencing continuous transformation, emerging as a significant global trend in the 21st Century. The industry's upward trajectory has captured the interest of both academic and professional communities. With its persistent growth, the need for eco-friendly coatings for metal packaging is on the rise, creating diverse career opportunities in coatings and packaging. In this dynamic landscape, industry leaders are challenged to develop fresh skill sets and gain a comprehensive understanding of the macro and micro factors influencing the demand for water-based coatings. Amidst these developments, maintaining a holistic perspective remains paramount.
Key Market Insights:
The Water-Based Metal Packaging Coatings market is characterized by several key market insights that shape its dynamics and trajectory. Firstly, the increasing emphasis on environmental concerns propels the demand for eco-friendly coating solutions within the metal packaging industry. Water-based coatings stand out as a preferred choice due to their lower environmental impact compared to solvent-based alternatives. Moreover, stringent regulatory requirements aimed at reducing volatile organic compounds (VOC) emissions are driving the adoption of water-based coatings, positioning them as a regulatory-driven market insight.
The versatility of water-based metal packaging coatings is yet another crucial insight. These coatings find applications across diverse sectors, including food and beverage, pharmaceuticals, and industrial domains. Their ability to adhere to various substrates and accommodate different metal types underscores their adaptability and market reach.
However, longer drying times and initial higher costs compared to solvent-based coatings hinder their widespread adoption. Nonetheless, continuous research and development efforts propel the market forward, fostering innovation in water-based coatings and leading to new formulations and application techniques that cater to evolving market needs.
Water-Based Metal Packaging Coatings Market Drivers:
The incorporation of cost-effective, high-quality coatings is driving growth within the Water-Based Metal Packaging Coatings market.
In a parallel manner, the Water-Based Metal Packaging Coatings market reflects a comparable trend. Just as developing nations offer high-quality medical treatments at reduced costs, the water-based coatings market provides industries with the advantage of applying advanced protective coatings to metal packaging at a relatively lower expense. These coatings' affordability does not compromise their effectiveness, as they leverage available resources to ensure product durability and quality. This economic advantage draws businesses seeking efficient packaging solutions, driving demand for water-based coatings. The cost efficiency of water-based coatings in the metal packaging realm aligns with the economic considerations observed in healthcare markets. Just as accessibility to high-quality healthcare services at affordable prices propels the medical tourism industry, developments in the water-based coatings' infrastructure and their availability at reasonable costs foster growth in the global market.
Protracted lead times are a significant concern, propelling the demand for efficient solutions in the Water-Based Metal Packaging Coatings market.
Developed countries often face protracted delays in the progression from the initial coating process to subsequent stages, potentially exacerbating issues for manufacturers. Prolonged lead times between coating application and packaging completion can hinder operational efficiency and product delivery timelines. Extended timelines in the coatings market might lead to compromised product quality and hinder supply chain performance. For instance, postponing the application of necessary protective coatings can leave metal packaging vulnerable to corrosion and damage, diminishing its overall functionality and potentially leading to subsequent complications. This interplay of time-sensitive considerations highlights the shared challenge of balancing efficiency and effectiveness across industries.
The escalating need for robust protection against corrosion and environmental factors is propelling the demand for advanced coatings within the Water-Based Metal Packaging Coatings market.
The rising prevalence of corrosion and degradation challenges, particularly in sectors relying on metal packaging, is driving the demand for advanced protective solutions in the Water-Based Metal Packaging Coating market. As industries face increasing pressures to ensure product integrity and longevity, the introduction of innovative coating technologies becomes crucial. These coatings act as a shield against the harmful effects of environmental factors, preventing corrosion and enhancing the durability of metal packaging. The growing awareness of the advantages of advanced coatings and their accessibility aligns with the heightened awareness of medical tourism, as both markets respond to evolving consumer needs and technological progress.
The surge in governmental investments towards research and development, infrastructure enhancement, and sustainability initiatives is propelling growth in the Water-Based Metal Packaging Coatings market.
The escalating commitment of governments towards fostering sustainable and advanced manufacturing practices is driving the Water-Based Metal Packaging Coatings market. Favorable regulatory frameworks, increased funding for innovation, and initiatives promoting eco-friendly coatings contribute significantly to the sector's growth. Furthermore, the proliferation of accessible information about coating formulations, their benefits, and optimal application methods plays a pivotal role in raising awareness and driving demand among industries.

Water-Based Metal Packaging Coatings Market Restraints and Challenges:
Cumbersome regulatory approval processes and challenges related to compatibility with various substrate materials pose significant constraints for the Water-Based Metal Packaging Coatings market.
The Water-Based Metal Packaging Coatings market faces comparable challenges. Some manufacturers may encounter issues stemming from the high costs charged by certain suppliers for coating materials, affecting overall operational expenses and profit margins. The Water-Based Metal Packaging coating sector faces limitations in insurance reimbursements or warranties, particularly when specific performance criteria are not met. Furthermore, coating manufacturers grapple with issues when expanding into international markets. Finally, the significance of aftercare resonates in the Water Based Metal Packaging Coating domain. While, the coatings industry must address post-application quality monitoring to ensure coatings' durability and performance over time, reflecting the shared concern of comprehensive, ongoing support.
Water-Based Metal Packaging Coatings Market Opportunities:
The Water-Based Metal Packaging Coatings market presents promising opportunities driven by the growing demand for sustainable packaging solutions. Increased environmental awareness and stringent regulations are propelling the adoption of water-based coatings that offer corrosion resistance and durability. The expansion of industries like food and beverages, pharmaceuticals, and personal care further boosts demand. Collaborations between manufacturers, research institutions, and regulatory bodies to develop innovative formulations and efficient application methods are opening avenues for advancements in this dynamic market.
WATER-BASED METAL PACKAGING COATINGS MARKET REPORT COVERAGE:
|
REPORT METRIC |
DETAILS |
|
Market Size Available |
2022 - 2030 |
|
Base Year |
2022 |
|
Forecast Period |
2023 - 2030 |
|
CAGR |
2.8% |
|
Segments Covered |
By Type, Application, and Region |
|
Various Analyses Covered |
Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
|
Regional Scope |
North America, Europe, APAC, Latin America, Middle East & Africa |
|
Key Companies Profiled |
The Sherwin-Williams Company, BASF SE, AkzoNobel N.V., PPG Industries, Inc., RPM International Inc., Asian Paints Limited, Axalta Coating Systems LLC Nippon Paint Holdings Co. Ltd., Kansai Paint Co. Ltd., Tikkurila OYJ. |
Acrylic
Polyester
Alkyd
Epoxy
Others
In the Water-Based Coatings Market, the segments Epoxy and Acrylic Coatings typically exhibit the highest and fastest growth rates, respectively. Epoxy coatings, known for their exceptional durability and resistance properties, often witness the highest growth due to their suitability for various applications, ranging from industrial and automotive to construction. The demand for robust protection against corrosion and wear contributes to the sustained popularity of epoxy coatings. On the other hand, Acrylic coatings experience rapid growth due to their versatility, ease of application, and ability to adhere well to diverse substrates. Their ability to provide good weather resistance, glossy finishes, and UV protection further adds to their appeal across industries. While Epoxy coatings tend to have the highest growth rate, "Acrylic" coatings often experience the fastest growth, driven by their wide-ranging applications and favorable performance characteristics.
Architectural
Industrial
The Architectural segment tends to have the highest growth, while the Industrial segment often experiences the fastest growth in the context of market segmentation based on application. The Architectural segment encompasses coatings used in residential, commercial, and institutional buildings, where the demand for aesthetics, durability, and protection against weathering drives steady growth. As construction and renovation activities continue, this segment maintains a robust trajectory.

North America
Asia-Pacific
Europe
South America
Middle East and Africa
The Asia-Pacific region often exhibits the largest market share of 38.5% in the Global Water-Based Metal Packaging Coatings Market and is anticipated to grow at the fastest rate as well during the forecast period. The Asia-Pacific region encompasses a diverse range of economies with rapidly expanding industrial sectors, construction activities, and consumer markets. This region's growth is fueled by factors such as urbanization, infrastructure development, increased manufacturing, and rising disposable income, driving significant demand for coatings across various applications.
COVID-19 Impact Analysis on the Global Water-Based Metal Packaging Coatings Market:
The Global Water-Based Metal Packaging Coatings Market experienced supply chain disruptions, reduced manufacturing activity, fluctuating demand for packaged goods, delayed projects, and export-import challenges due to the COVID-19 pandemic. Economic uncertainty, safety protocols, and a shift towards sustainability further influenced the market's dynamics, prompting the industry to adapt and recover amid changing consumer behaviors and market conditions.
Latest Trends/ Developments:
The Asia-Pacific region exerts significant dominance over the packaging coatings market, primarily driven by the escalating requirements from various sectors, including food and beverages, marine, architectural, packaging, and healthcare industries.
The surging interest in novel plastic technologies aimed at creating recyclable and ecologically sustainable solutions, enriched with specific attributes like lightweight durability, moisture resistance, and chemical resilience, is anticipated to play a pivotal role in fostering the growth dynamics of the packaging coatings market.
Key Players:
The Sherwin-Williams Company
BASF SE
AkzoNobel N.V.
PPG Industries
Inc., RPM International Inc.
Asian Paints Limited
Axalta Coating Systems LLC
Nippon Paint Holdings Co. Ltd.
Kansai Paint Co. Ltd.
Tikkurila OYJ.
In August 2021, The Sherwin-Williams Company announced an agreement to acquire the European industrial coatings business of Sika AG.
In February 2021, PPG announced that it had completed its acquisition of VersaFlex from DalFort Capital Partners.
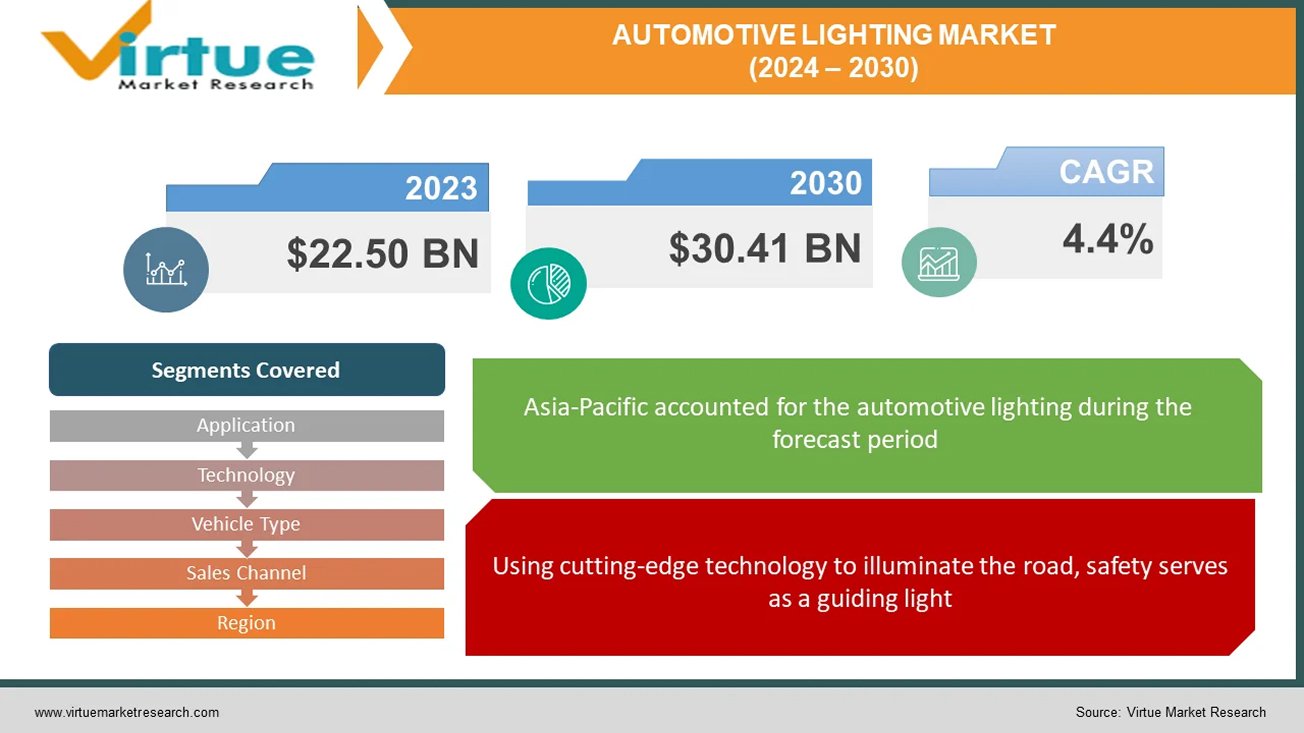
Global automotive lighting refers to all vehicle lighting systems, from headlamps that illuminate the road to taillights that communicate movements. They guarantee motorists and other road users alike safety, visibility, and style. While taillights frequently use LEDs for improved visibility, headlights are available in a variety of technologies, including LED and laser. Interior illumination, DRLs, and signal lights all have a role to play. This market, which was estimated to be worth $33.64 billion in 2022, is anticipated to rise to $67.39 billion by 2030 because of laws, luxury tastes, safety concerns, and technological developments like OLED taillights and adaptive headlights. Anticipate a future dominated by intelligent, connected, personalized, and sustainable lighting systems that enhance the safety, efficiency, and aesthetic appeal of automobiles.
Car lighting works its magic to provide safety, visibility, and style. Headlights cut through the night, taillights express intent, and interiors shine with comfort. The billion-dollar global business is expected to rise due to consumer demand for high-end experiences, safer roads, and cutting-edge technology. Imagine dynamic messages being painted by taillights, headlights that adjust to the road, and interiors that customize their atmosphere. Driven by technological advancements like linked systems and laser beams, this future is calling. Anticipate even more visually attractive, environmentally friendly, and intelligent lighting to illuminate the way ahead, making cars safer, more efficient, and unquestionably cooler.
In the market for automobile lighting, safety is the driving force behind demand from the public and laws. While automated high beams smoothly react to traffic, adaptive headlights modify their beams so as not to blind other people. With visually striking displays, dynamic taillights convey intentions for braking and turning. Beyond these developments, integrated pedestrian identification and lane departure alerts will soon make roads safer and brighter for everyone.
Luxurious automobile lighting creates a distinct visual identity that goes beyond simple illumination. Personalized interior lighting customizes the driving experience by setting the mood with a range of colours and intensities, while intricate designs and distinctive DRLs modify exteriors. As you approach your automobile at night, welcoming lights lead the way, resulting in an interior that is perfectly lit. Not only is this symphony of light aesthetically pleasing, but it also stands as a tribute to luxury. Upcoming developments like gesture-controlled lighting and holographic displays promise to further enhance the experience.
The worldwide automotive lighting market is undergoing a significant transition towards energy-efficient solutions, as environmental concerns gain prominence. LED technology is leading the way, providing a ray of hope for the environment and drivers alike. LED lights beam brighter and use a lot less energy than conventional halogen lamps. There are some tangible advantages to this. For drivers, this translates to increased fuel economy, which lowers petrol prices and lessens reliance on fossil fuels. Greater air quality and a reduction in the transport sector's contribution to climate change are the results of reduced overall emissions.
Although the global automotive lighting business is booming, there are still unknowns. Difficulties impede growth even as innovation propels it with eye catching features like laser beams and adaptable headlights. These technologies are luxury items due to their high cost and difficult integration, which puts producers' abilities to the test. The worldwide patchwork created by unclear legislation limits the potential of innovation. Durability issues persist, particularly when complex systems are subjected to challenging conditions. Ultimately, a lot of drivers still don't fully understand how these improvements can help them. Together, we can overcome these obstacles. The keys to reducing costs are improved production, more seamless integration, and unified regulations. Their full potential can be realized by educating customers about the safety, efficiency, and aesthetic value of these lighting wonders. By working together, we can pave the way for an even brighter and safer future for vehicle lighting.
It is made possible by advanced LED technology, which gives drivers the ability to customize their illumination for the highest level of comfort and flair. Consumers that care about the environment want greener products, and vehicle lighting complies. While solar- and self-powered lighting technologies offer a future powered by clean energy, energy-efficient LEDs lower pollution. The advent of connected lighting systems heralds a new age. Envision automobiles interacting with infrastructure and one another to minimize accidents and enhance traffic efficiency. Integrated headlights with pedestrian recognition provide unmatched safety, while dramatic taillights with eye-catching displays alert onlookers to your intentions. The possibilities are endless in the future. Gesture-controlled interior illumination, holographic displays projected onto the road, and even light fixtures with self-healing capabilities.

Due to laws requiring safety features like headlights, taillights, and brake lights, exterior lighting presently holds the most market share in the vehicle lighting industry. The dominance of this market is partly attributed to advancements in safety-focused technologies such as adaptive headlights and daytime running lights. The market value of external lighting is increased by the quick adoption of technology like LED bulbs and laser lights, which improve performance and aesthetics. Conversely, the interior lighting market is expected to increase at the fastest rate in the upcoming years. Innovations like ambient lighting and technology breakthroughs like LED and OLED displays, driven by consumer demand for comfort and personalisation, open new possibilities. The spread of sophisticated interior lighting systems is further driven by the growing emphasis on safety and the expansion of the luxury car market.
The worldwide vehicle lighting market is currently dominated by halogen because of its more affordable price, advanced technology, and useful illumination. With its dependable supply chain and affordable option for manufacturers and cost-conscious customers, halogen holds the biggest market share. The fastest-growing market right now is LEDs, which are predicted to shortly overtake halogen. The rapid expansion of LEDs is driven by their higher efficiency, longer lifespan, flexibility in design, and technological breakthroughs including enhanced brightness. Because LEDs use less energy and produce fewer emissions and better fuel economy, they are becoming more and more popular in the changing automotive lighting market.
Passenger automobiles rule the worldwide automotive lighting market. The sheer number of passenger cars produced which surpasses that of business vehicles and fuels the need for lighting systems is the primary cause of this popularity. The growing demand for personal automobiles in developing nations is a result of rising disposable income, which in turn drives the rise of the passenger car market. The importance that consumers place on safety and aesthetics elements helps to drive market expansion. But in the upcoming years, the market for electric and hybrid cars is expected to develop at the quickest rate. The exponential rise of the worldwide electric car market, which is still expanding and shows no signs of slowing down, is what is driving this surge. Specialised lighting solutions are required since electric and hybrid vehicles have different lighting requirements because of their specific functionality and design aesthetics.
Most lighting systems sold nowadays are sold by OEMs (Original Equipment Manufacturers), primarily because manufacturers pre-install lighting systems in new cars. But in the next years, the aftermarket is expected to develop at the quickest rate. This spike in demand for replacement parts, especially lighting systems, can be linked to several variables, one of them being the average age of cars. The industry is expanding because of consumers' growing desire to personalise their cars with aftermarket lighting upgrades such LED upgrades and decorative lighting. The availability and affordability of technologies like adaptive headlights and laser lights in the aftermarket, together with other advancements in lighting technology, are driving demand even more. Moreover, the growing market for electric cars (EVs).
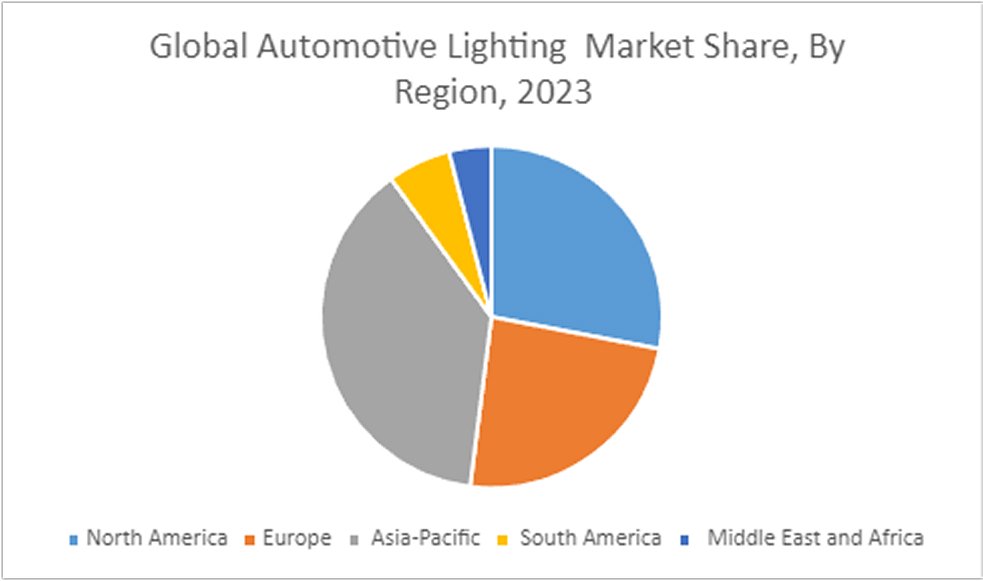
Throughout the forecast period, Asia Pacific is anticipated to be the automotive lighting market with the highest profitability. Over the past few years, Asia Pacific countries like China and India have seen notable increases in automotive manufacturing and sales, primarily in the medium-to premium luxury car segment. Asia Pacific is predicted to see an increase in the manufacturing of passenger cars, with India experiencing the strongest growth rate. Depending on the state of the national economy, the area offers a suitable selection of both high-end and cheap cars. For instance, there is a substantial demand for halogen, Xenon/HID, and LED since China and India produce more economy and mid-range automobiles. On the other hand, luxury car adoption rates are greater in South Korea and Japan, where LED lighting is the norm.
A brief shadow was thrown by COVID-19 over the worldwide automotive lighting market. Production was stopped by lockdowns and supply chain disruptions, while luxury lighting upgrades were shelved by consumers on a tight budget. Resources became scarce, and R&D stagnated. Still, the market is recovering thanks to resurgent demand and rearranged priorities. While energy-efficient LEDs are being pushed towards adoption by sustainability, safety concerns are driving interest in features like pedestrian detection and adaptive headlights. The digital push of the epidemic creates opportunities for intelligent, networked lighting systems that may interact with infrastructure and other cars. Ultimately, the industry is positioned to shine brighter, focused on safety, sustainability, and a connected future, even though the pandemic dimmed its brilliance.
A development collaboration between OSRAM Continental and REHAU aims to incorporate lighting into external components, providing automobile manufacturers with innovative lighting options that improve functionality and design flexibility. For rear combination lamps, Hella unveiled a revolutionary lighting innovation called Hella FlatLight technology. A Memorandum of Understanding (MoU) was signed by Samvardhana Motherson Automotive Systems Group BV (SMRPBV), a division of Motherson Group, and Marelli Automotive Lighting to investigate a technology collaboration focused on intelligently lighted external body components. Valeo debuted their revolutionary 360° lighting system at the Shanghai Auto Show. This technology surrounds the car with a band of light, projecting instantaneous, clear signs that other drivers can see from a distance. Pedestrians, cyclists, and scooter riders are especially susceptible to these signals
The COVID-19 pandemic disrupted supply chains, led to reduced manufacturing activity, and caused fluctuating demand for Water-Based Metal Packaging Coatings due to economic uncertainties and safety measures.
Key drivers of growth in the Water-Based Metal Packaging coating market include increasing environmental awareness, stricter regulations, and the demand for sustainable and low-VOC coating solutions.
Regions such as Asia-Pacific, Europe, and North America exhibit some of the highest demands for Water-Based Metal Packaging Coatings due to industrial growth and sustainability initiatives.
The regulatory landscape presents challenges of compliance with stricter environmental standards and opportunities for innovation in sustainable and low-VOC formulations in the Water-Based Metal Packaging Coatings Market.
Water-based coatings offer advantages such as reduced volatile organic compounds (VOCs), lower environmental impact, and safer application processes compared to traditional solvent-based coatings in metal packaging applications.
Joining thousands of companies around the world committed to making the Excellent Business Solutions.
Specify your preferred Countries, Segments, or timeframes
Unlock Country Level Outlook, Trends, Cross-country Comparability, or supply Chain Variations.


Analyst Support
Every order comes with Analyst Support.

Customization
We offer customization to cater your needs to fullest.

Verified Analysis
We value integrity, quality and authenticity the most.

