
Industrial Lubricants Market
The market size was estimated at USD 77 billion in 2025, and is projected to reach 88.83 billion in 2030, growing at a CAGR of 2.9% from 2026 to 2030.
Explore reportIn 2022, the Global Thermal Copper Pillar Bump Market was valued at USD 1.3 billion and is projected to reach a market size of USD 2.12 billion by 2030. Over the forecast period of 2023-2030, the market is projected to grow at a CAGR of 6.3%.

Industry Overview:
The thermal copper pillar bump, also referred to as the "thermal bump," is a thermoelectric component used in flip chip interconnects (specifically copper pillar solder bumps) for electronics and optoelectronic packagings, such as flip chip packaging of CPU and GPU integrated circuits (chips), semiconductor optical amplifiers (SOA), and laser diodes. In contrast to traditional solder bumps, which offer an electrical channel and a mechanical connection to the package, thermal bumps work as solid-state heat pumps and add local thermal management capabilities to the surface of a chip or another electrical component. The issues that flip chip packages encounter as the bump pitch size continues to decrease can be addressed with copper pillar bumping, which is a viable approach. A common type of flip chip interface that gives benefits in many designs while satisfying present and future ROHS regulations is the copper pillar bump. For applications requiring a blend of fine pitch, ROHS/Green compliance, low cost, and electromigration performance, such as embedded processors, transceivers, application processors, power management, ASICs, baseband, and SOCs, it is a great connectivity option. By using TCFC (Thermal Compression Flip-Chip) technology, copper pillars are terminals that are used to "flip-chip" IC chips to a substrate in a semiconductor package. On the aluminum electrode pads of an IC chip, copper pillars are created. Due to an increase in pin count with tiny pad pitches integrated on an IC chip, copper pillar interconnects are in increased demand. Through the use of fine plating pattern formation techniques, uniformly sized copper pillars may be created on silicon wafers.
The increasing need for high connectivity devices, technological superiority over wire bond connections, capacity to maintain high package densities and rising circuit durability are some of the market-driving drivers. The development of copper pillar and micro bumping metallurgy, as well as its widespread use in consumer electronics and mobile phones, are driving up demand for flip-chip technology at the moment. The most cutting-edge manufacturing methods are supported by current bumping techniques, allowing the flip-chip process to be changed to address new issues. The market for flip-chip technology is expanding due to rising consumer, computer, and mobile wireless application demand. Flip chips are mostly used in electrical connections and electronic packaging. The Copper Pillar Bump is a new flip-chip interconnect that offers design benefits to satisfy both present-day and foreseeable demands for electronic devices. Flip chip has also transformed the markets for portable devices and electric vehicles by establishing itself as the optimum product for electrical interconnections. One of the main elements influencing the market's outlook favorably is the global electronics industry's rapid rise. For device downsizing, increased electrical efficiency, and low power consumption, flip-chip technology is widely used in consumer electronics and robotic applications. Additionally, several technical developments, including the Internet of Things (IoT) integration of linked devices and the use of flip-chip technology for enhanced microwave and ultrasonic operations, are helping the industry expand. The market is estimated to rise as a result of several other reasons, such as the expanding need for circuit miniaturization in microelectronic devices and intensive research and development (R&D) efforts.
COVID-19 pandemic impact on Thermal Copper Pillar Bump Market
In recent years, the global thermal copper pillar bump market has experienced rapid revenue growth; however, the market has recently seen a sharp fall as a result of the important electronics manufacturing industries being temporarily shut down, largely to stop the spread of COVID-19. Additionally, this pandemic has had a significant effect on the global supply chain by affecting suppliers through shortages of components, materials, and finished goods as well as by lowering consumer spending in China on products that depend on semiconductors, such as consumer electronics, automobiles, and other products. The long-term shutdown in China caused by the COVID-19 epidemic has an impact on all production bases and industries there, which has an impact on the market for flip-chip technology. As a result, the global supply chain model must be changed in the semiconductor industry, which is predicted to have a favorable effect on the market's growth in the future.
MARKET DRIVERS:
An increase in the demand for high-frequency applications and a rise in the necessity for circuit miniaturization in microelectronic devices both contribute to the market's expansion
The adoption of thermal copper pillar bump in microelectronic devices is driven by the rise in demand for smaller electronic devices, increased electrical efficiency, and reduced power consumption. Flip chips are used more frequently in the microwave and ultrasonic operations because they improve the efficiency of electrical machinery that runs at high frequencies. Flip chips' widespread use in electrical gadgets is driven by these particular characteristics. Additionally, it is anticipated that during the projected period, continuous R&D initiatives by key competitors in the global market would present new growth possibilities for the thermal copper pillar bump market. In December 2021, Thomasnet introduced Hi-Watty Light, a high-tech method for contacting microelectronic components without housing that has applications in the flip-chip assembly and automated semiconductor test systems for automotive engineering. Additionally, it can be applied to the semiconductor, medical, automotive, and aerospace industries. As a result, increasing miniaturization demands are encouraging the usage of flip chips across a variety of industries, which is fueling the expansion of this market. On the other hand, it is anticipated that technical advances made possible by facilities for research and development and investments made by major market players will present lucrative chances for the growth of the overall market. The widespread usage of flip chips in communications applications such as network systems, cellular base stations, optoelectronics, telecommunication switching, and wireless goods is another factor fueling the market's expansion.
The market's expansion is being fueled by technological advancements in wire bonding.
Due to their improved qualities, including their compact size, robust structure, increased efficiency, and high-frequency application support at a relatively low cost, flip chips have gradually replaced wire bonding packaging. Wire bonding is currently becoming more and more common in the packaging industry. Flip chips, however, are replacing wire bonded technology due to their remarkable qualities, including higher I/O capability, superior thermal & electrical performance, and substrate flexibility for varying performance requirements. As a result, the flip-chip market forecast is estimated to experience rapid growth in the future. Flip chips have been pushed to take the place of wire bond technology in products like cellphones, PC processors, and gaming consoles as a result of these criteria. Additionally, a surge in the utilization of flip chips in modern electronics is anticipated to accelerate the expansion of the thermal copper pillar bump market in the future.
MARKET RESTRAINTS:
The market's expansion is hampered by the usage of additional wafer bumping and more expensive substrate.
The main obstacle to the widespread use of thermal copper pillar bump is the high cost of the packaging solutions for flip chips, which are produced by suppliers of wafer manufacturing, substrate, and assembly/packing services. Due to their incredibly sophisticated architecture and small size, these chips' number of input and output ports cannot be altered after manufacturing. Thus, these elements taken as a whole prevent the market from expanding. The flip-chip package is no longer a viable alternative for customers due to the increased costs of production and packaging. By providing flip-chip packaging alternatives on standard bis-maleimide triazine resin substrates, quad flat pack no leads (QFN), and standard lead frames (FCSOL), the packaging and assembly companies have taken efforts toward giving cost-effective solutions.
The need for extremely flat surfaces for heat dissipation and the bumping of beads cause stiff and short beads to be prone to shattering
Flip Chips bump and flip semiconductor die onto substrates to connect them to the substrate. Directly on the input-output pads of the die, bumps are often arranged in an array covering the full die surface. Since the chip and circuit board are directly connected, the wire is shorter, which reduces resistance and speeds up the signal transmission. However, these close-spaced bumps lack mechanical strength and are susceptible to cracking at higher temperatures in the event of a thermal expansion mismatch. Efficiency in heat removal and dissipation is another difficulty that arises because amplifiers or other components are suspended over a substrate on metal bumps that serve as thermal standoffs. Using a flip-chip device and a low-loss substrate is a typical design strategy.
GLOBAL THERMAL COPPER PILLAR BUMP MARKET REPORT COVERAGE:
|
REPORT METRIC |
DETAILS |
|
Market Size Available |
2022 - 2030 |
|
Base Year |
2022 |
|
Forecast Period |
2023 - 2030 |
|
CAGR |
6.3% |
|
Segments Covered |
By Packaging Technology, Vertical and Region |
|
Various Analyses Covered |
Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
|
Regional Scope |
North America, Europe, APAC, Latin America, Middle East & Africa |
|
Key Companies Profiled |
Shinko Electric Industries Co., LTD., 3M Company, Amkor Technology, Inc., Advanced Micro Devices, Inc., Fujitsu Limited, Taiwan Semiconductor Manufacturing Company |
This research report on the global Thermal Copper Pillar Bump Market has been segmented and sub-segmented based on Packaging Technology, Vertical, and region.
3D IC
2.5D IC
2D IC
Based on Packaging Technology, the Thermal Copper Pillar Bump market is bifurcated into 2.5D IC, 2D IC, and 3D IC. Using copper pillars instead of conventional solders has additional benefits, such as increased input-output density, enhanced thermal conductivity, and improved electromigration resistance.AMD will be the first manufacturer to introduce copper hybrid bonding-capable chips in August 2021. This cutting-edge die-stacking technology enables the next generation of 3D-like devices and packages. In contrast to current chip-stacking interconnect systems, hybrid bonding links, and stacks chips utilizing microscopic copper-to-copper interconnects, which offer increased density and bandwidth. The connectivity systems in the package for Intel's 3D CPU, HBM, and other chips use minute copper micro bumps and a flip-chip technique. To improve the overall performance of the electronic gadget and support the market's growth, copper pillar bumping technology is thus constantly evolving.
Electronics
Healthcare
Automotive and Transport
IT and Telecommunication
Aerospace and Defense
Others
Based on End User, the Thermal Copper Pillar Bump market is segmented into Electronics, Industrial, Automotive, IT & Telecom, Aerospace & Defense, Healthcare & Life Sciences, and Others. In terms of application, the military & defence sectors accounted for a sizable portion of the Flip Chip market in 2021. This is due to the demand for automated weapons, sophisticated security measures, and portable and small military equipment. This is a result of the increased use of automated security systems, sensor technologies, and cutting-edge weapons and ammunition. As a result, flip-chip technology is required for military computing platforms. The necessity to cool down components to lower temperatures for military needs has prompted the development of an indium micropump-based technology. Flip chips are therefore frequently used because of their high-frequency operations. Qorvo, a semiconductor company, said in May 2020 that it had signed a new contract with the United States Department of Defense (DoD). The objective is to advance the technological advancement of copper-pillar-on-GaN flip-chips. Thus, expanding research and applications in the military and defence sectors contribute to the expansion of the flip-chip industry.
North America
Europe
Asia-Pacific
Rest of the World
Asia Pacific Thermal Copper Pillar Bump Market is anticipated to expand quickly during the forecast period. The consumer electronics industry accounts for the majority of the demand for Thermal Copper Pillar Bump. 37% of the global market was accounted for by the APAC (Asia-Pacific) region in 2021. This is a result of the wide availability of raw materials in Asian nations and the expansion of research into MEMS and system-on-a-chip (SoC) technologies for flip chips. The market for flip chips is expanding due to causes including rising research into micro electrical mechanical systems (MEMS) technologies, rising demand for portable and compact circuit devices, and the requirement for higher frequency data transmission between devices.
Major Key Players in the Market
Shinko Electric Industries Co., LTD.
3M Company
Amkor Technology, Inc.
Advanced Micro Devices, Inc.
Fujitsu Limited
Taiwan Semiconductor Manufacturing Company
Notable happenings in the Global Thermal Copper Pillar Bump Market in the recent past:
Expansion- In March 2022, Samsung Electro-Mechanics and LG Innotek, two of the major producers of IT components in Asia-Pacific, announced plans to expand new markets with a next-generation semiconductor packaging substrate known as flip chip ball grid array, increasing investment in this area to compete against Japanese and Taiwanese rivals.
Expansion- In November 2021, Amkor Technology Inc., a top supplier of semiconductor packaging and test services announced the construction of a cutting-edge smart factory in Bac Ninh, Vietnam. The new factory's initial phase will be devoted to offering cutting-edge system in package (SiP) assembly and test solutions to the top semiconductor and electronic manufacturing firms across the world.
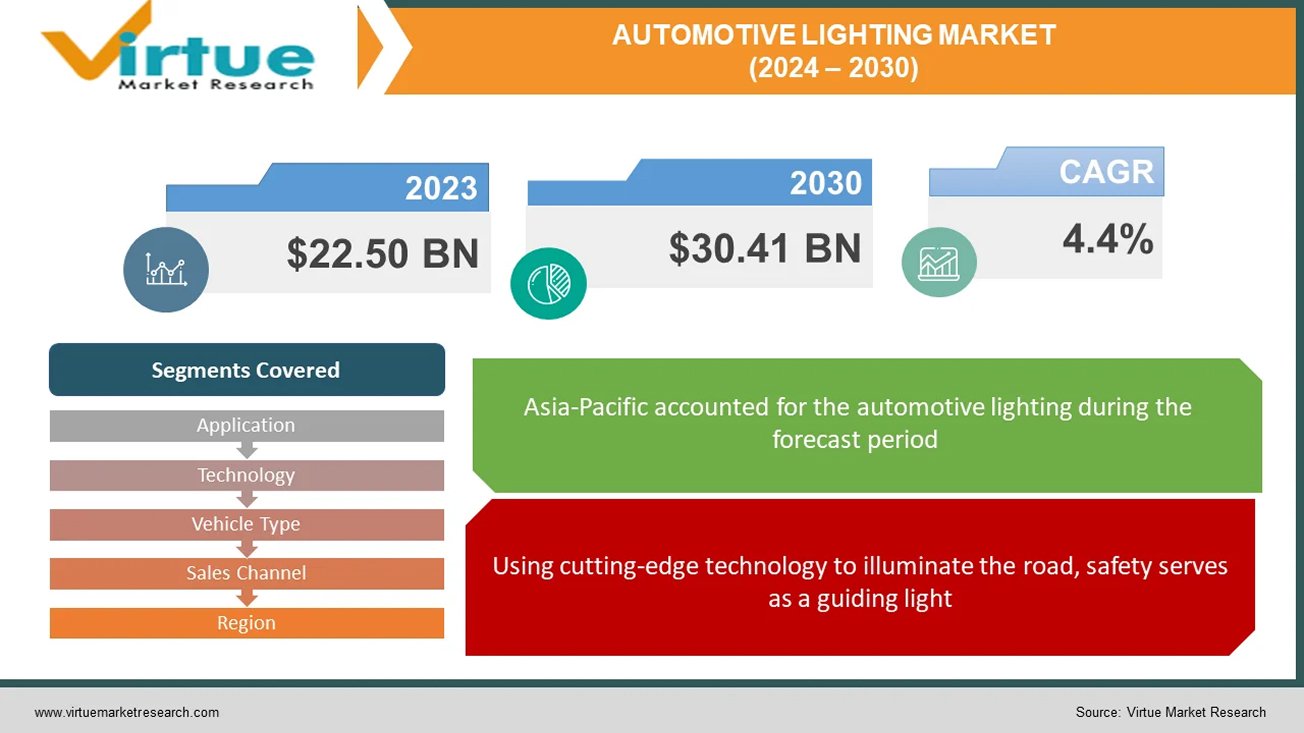
Global automotive lighting refers to all vehicle lighting systems, from headlamps that illuminate the road to taillights that communicate movements. They guarantee motorists and other road users alike safety, visibility, and style. While taillights frequently use LEDs for improved visibility, headlights are available in a variety of technologies, including LED and laser. Interior illumination, DRLs, and signal lights all have a role to play. This market, which was estimated to be worth $33.64 billion in 2022, is anticipated to rise to $67.39 billion by 2030 because of laws, luxury tastes, safety concerns, and technological developments like OLED taillights and adaptive headlights. Anticipate a future dominated by intelligent, connected, personalized, and sustainable lighting systems that enhance the safety, efficiency, and aesthetic appeal of automobiles.
Car lighting works its magic to provide safety, visibility, and style. Headlights cut through the night, taillights express intent, and interiors shine with comfort. The billion-dollar global business is expected to rise due to consumer demand for high-end experiences, safer roads, and cutting-edge technology. Imagine dynamic messages being painted by taillights, headlights that adjust to the road, and interiors that customize their atmosphere. Driven by technological advancements like linked systems and laser beams, this future is calling. Anticipate even more visually attractive, environmentally friendly, and intelligent lighting to illuminate the way ahead, making cars safer, more efficient, and unquestionably cooler.
In the market for automobile lighting, safety is the driving force behind demand from the public and laws. While automated high beams smoothly react to traffic, adaptive headlights modify their beams so as not to blind other people. With visually striking displays, dynamic taillights convey intentions for braking and turning. Beyond these developments, integrated pedestrian identification and lane departure alerts will soon make roads safer and brighter for everyone.
Luxurious automobile lighting creates a distinct visual identity that goes beyond simple illumination. Personalized interior lighting customizes the driving experience by setting the mood with a range of colours and intensities, while intricate designs and distinctive DRLs modify exteriors. As you approach your automobile at night, welcoming lights lead the way, resulting in an interior that is perfectly lit. Not only is this symphony of light aesthetically pleasing, but it also stands as a tribute to luxury. Upcoming developments like gesture-controlled lighting and holographic displays promise to further enhance the experience.
The worldwide automotive lighting market is undergoing a significant transition towards energy-efficient solutions, as environmental concerns gain prominence. LED technology is leading the way, providing a ray of hope for the environment and drivers alike. LED lights beam brighter and use a lot less energy than conventional halogen lamps. There are some tangible advantages to this. For drivers, this translates to increased fuel economy, which lowers petrol prices and lessens reliance on fossil fuels. Greater air quality and a reduction in the transport sector's contribution to climate change are the results of reduced overall emissions.
Although the global automotive lighting business is booming, there are still unknowns. Difficulties impede growth even as innovation propels it with eye catching features like laser beams and adaptable headlights. These technologies are luxury items due to their high cost and difficult integration, which puts producers' abilities to the test. The worldwide patchwork created by unclear legislation limits the potential of innovation. Durability issues persist, particularly when complex systems are subjected to challenging conditions. Ultimately, a lot of drivers still don't fully understand how these improvements can help them. Together, we can overcome these obstacles. The keys to reducing costs are improved production, more seamless integration, and unified regulations. Their full potential can be realized by educating customers about the safety, efficiency, and aesthetic value of these lighting wonders. By working together, we can pave the way for an even brighter and safer future for vehicle lighting.
It is made possible by advanced LED technology, which gives drivers the ability to customize their illumination for the highest level of comfort and flair. Consumers that care about the environment want greener products, and vehicle lighting complies. While solar- and self-powered lighting technologies offer a future powered by clean energy, energy-efficient LEDs lower pollution. The advent of connected lighting systems heralds a new age. Envision automobiles interacting with infrastructure and one another to minimize accidents and enhance traffic efficiency. Integrated headlights with pedestrian recognition provide unmatched safety, while dramatic taillights with eye-catching displays alert onlookers to your intentions. The possibilities are endless in the future. Gesture-controlled interior illumination, holographic displays projected onto the road, and even light fixtures with self-healing capabilities.

Due to laws requiring safety features like headlights, taillights, and brake lights, exterior lighting presently holds the most market share in the vehicle lighting industry. The dominance of this market is partly attributed to advancements in safety-focused technologies such as adaptive headlights and daytime running lights. The market value of external lighting is increased by the quick adoption of technology like LED bulbs and laser lights, which improve performance and aesthetics. Conversely, the interior lighting market is expected to increase at the fastest rate in the upcoming years. Innovations like ambient lighting and technology breakthroughs like LED and OLED displays, driven by consumer demand for comfort and personalisation, open new possibilities. The spread of sophisticated interior lighting systems is further driven by the growing emphasis on safety and the expansion of the luxury car market.
The worldwide vehicle lighting market is currently dominated by halogen because of its more affordable price, advanced technology, and useful illumination. With its dependable supply chain and affordable option for manufacturers and cost-conscious customers, halogen holds the biggest market share. The fastest-growing market right now is LEDs, which are predicted to shortly overtake halogen. The rapid expansion of LEDs is driven by their higher efficiency, longer lifespan, flexibility in design, and technological breakthroughs including enhanced brightness. Because LEDs use less energy and produce fewer emissions and better fuel economy, they are becoming more and more popular in the changing automotive lighting market.
Passenger automobiles rule the worldwide automotive lighting market. The sheer number of passenger cars produced which surpasses that of business vehicles and fuels the need for lighting systems is the primary cause of this popularity. The growing demand for personal automobiles in developing nations is a result of rising disposable income, which in turn drives the rise of the passenger car market. The importance that consumers place on safety and aesthetics elements helps to drive market expansion. But in the upcoming years, the market for electric and hybrid cars is expected to develop at the quickest rate. The exponential rise of the worldwide electric car market, which is still expanding and shows no signs of slowing down, is what is driving this surge. Specialised lighting solutions are required since electric and hybrid vehicles have different lighting requirements because of their specific functionality and design aesthetics.
Most lighting systems sold nowadays are sold by OEMs (Original Equipment Manufacturers), primarily because manufacturers pre-install lighting systems in new cars. But in the next years, the aftermarket is expected to develop at the quickest rate. This spike in demand for replacement parts, especially lighting systems, can be linked to several variables, one of them being the average age of cars. The industry is expanding because of consumers' growing desire to personalise their cars with aftermarket lighting upgrades such LED upgrades and decorative lighting. The availability and affordability of technologies like adaptive headlights and laser lights in the aftermarket, together with other advancements in lighting technology, are driving demand even more. Moreover, the growing market for electric cars (EVs).
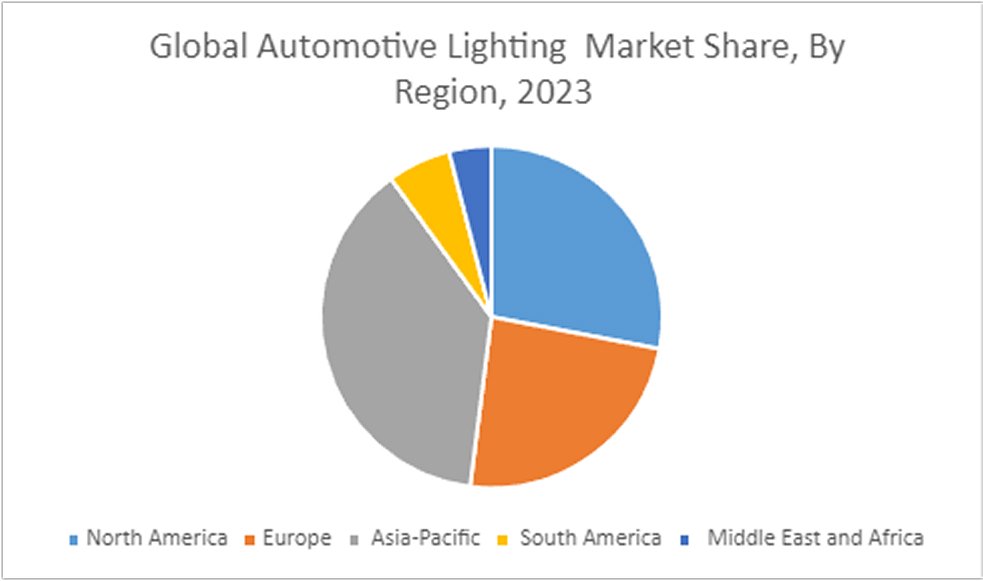
Throughout the forecast period, Asia Pacific is anticipated to be the automotive lighting market with the highest profitability. Over the past few years, Asia Pacific countries like China and India have seen notable increases in automotive manufacturing and sales, primarily in the medium-to premium luxury car segment. Asia Pacific is predicted to see an increase in the manufacturing of passenger cars, with India experiencing the strongest growth rate. Depending on the state of the national economy, the area offers a suitable selection of both high-end and cheap cars. For instance, there is a substantial demand for halogen, Xenon/HID, and LED since China and India produce more economy and mid-range automobiles. On the other hand, luxury car adoption rates are greater in South Korea and Japan, where LED lighting is the norm.
A brief shadow was thrown by COVID-19 over the worldwide automotive lighting market. Production was stopped by lockdowns and supply chain disruptions, while luxury lighting upgrades were shelved by consumers on a tight budget. Resources became scarce, and R&D stagnated. Still, the market is recovering thanks to resurgent demand and rearranged priorities. While energy-efficient LEDs are being pushed towards adoption by sustainability, safety concerns are driving interest in features like pedestrian detection and adaptive headlights. The digital push of the epidemic creates opportunities for intelligent, networked lighting systems that may interact with infrastructure and other cars. Ultimately, the industry is positioned to shine brighter, focused on safety, sustainability, and a connected future, even though the pandemic dimmed its brilliance.
A development collaboration between OSRAM Continental and REHAU aims to incorporate lighting into external components, providing automobile manufacturers with innovative lighting options that improve functionality and design flexibility. For rear combination lamps, Hella unveiled a revolutionary lighting innovation called Hella FlatLight technology. A Memorandum of Understanding (MoU) was signed by Samvardhana Motherson Automotive Systems Group BV (SMRPBV), a division of Motherson Group, and Marelli Automotive Lighting to investigate a technology collaboration focused on intelligently lighted external body components. Valeo debuted their revolutionary 360° lighting system at the Shanghai Auto Show. This technology surrounds the car with a band of light, projecting instantaneous, clear signs that other drivers can see from a distance. Pedestrians, cyclists, and scooter riders are especially susceptible to these signals
Joining thousands of companies around the world committed to making the Excellent Business Solutions.
Specify your preferred Countries, Segments, or timeframes
Unlock Country Level Outlook, Trends, Cross-country Comparability, or supply Chain Variations.


Analyst Support
Every order comes with Analyst Support.

Customization
We offer customization to cater your needs to fullest.

Verified Analysis
We value integrity, quality and authenticity the most.

